Accounting is a vital function in any organization, serving as the backbone for financial decision-making and compliance. It encompasses a variety of practices and disciplines, each tailored to meet specific needs. In this post, we will explore the different types of accounting, each with its unique purpose and significance in the business world.
1. Financial Accounting
Financial accounting is primarily concerned with preparing financial statements that provide a snapshot of a company's financial health to external stakeholders.
1.1 Definition and Purpose
Financial accounting involves recording, summarizing, and reporting financial transactions over a specific period. The primary goal is to accurately represent an organization’s financial position and performance to external parties such as investors, creditors, and regulatory agencies.
1.2 Key Financial Statements
The main financial statements produced through financial accounting include:
- Balance Sheet: A snapshot of an organization's assets, liabilities, and equity at a specific point in time.
- Income Statement: The profit and loss statement summarizes revenues and expenses over a period to show net income or loss.
- Cash Flow Statement: This statement provides insights into cash inflows and outflows from operating, investing, and financing activities.
Each of these statements plays a crucial role in evaluating a company's financial health.
1.3 Importance for Stakeholders
Financial statements are essential for stakeholders who rely on accurate information for decision-making. Investors use these reports to assess the viability of their investments, while creditors evaluate the creditworthiness of businesses before extending loans.
2. Management Accounting
Management accounting focuses on providing internal management with relevant financial information for strategic decision-making.
2.1 Definition and Role
Management accounting involves analyzing financial data to aid internal management in planning, controlling operations, and making informed decisions. Unlike financial accounting, which is primarily historical, management accounting emphasizes future projections.
2.2 Tools and Techniques
Key tools used in management accounting include:
- Budgeting: Establishing financial plans for future periods.
- Forecasting: Predicting future revenues and expenses based on historical data.
- Variance Analysis: Comparing actual performance against budgeted figures to identify discrepancies.
These tools help management make informed decisions that align with organizational goals.
2.3 Case Studies
For example, a manufacturing company may use management accounting techniques to analyze production costs closely. By identifying inefficiencies in the production process through variance analysis, management can implement changes that lead to significant cost savings.
3. Cost Accounting
Cost accounting analyzes production costs to help organizations improve profitability and efficiency.
3.1 Definition and Objectives
Cost accounting focuses on capturing all costs associated with production processes to understand where money is being spent. Its objectives include controlling costs, setting prices, and improving profitability.
3.2 Types of Cost Accounting Methods
Common methods include:
- Job Order Costing: Tracking costs for specific jobs or batches.
- Process Costing: Averaging costs over large quantities of identical products.
- Activity-Based Costing (ABC): Allocating costs based on activities that drive expenses.
Each method provides unique insights into cost structures.
3.3 Real-world Applications
A company may use job order costing when producing custom products. By accurately tracking costs associated with each job, management can determine pricing strategies that ensure profitability while remaining competitive.
4. Tax Accounting
Tax accounting ensures compliance with tax laws while optimizing tax liabilities for individuals and organizations.
4.1 Overview of Tax Regulations
Tax accountants specialize in understanding complex tax regulations at local, state, and federal levels. They ensure that individuals and businesses comply with tax laws while maximizing deductions and credits available to them.
4.2 Tax Planning Strategies
Effective tax planning involves strategies such as:
- Timing income and expenses to minimize tax liabilities.
- Taking advantage of tax credits.
- Utilizing retirement accounts for tax deferral.
These strategies help individuals and businesses manage their tax burdens effectively.
4.3 Importance of Accurate Reporting
Accurate tax reporting is crucial; mistakes can lead to audits or penalties from tax authorities. Tax accountants play a vital role in ensuring compliance while minimizing risks associated with inaccurate reporting.
5. Auditing Accounting
Auditing involves examining financial records to ensure accuracy and compliance with established standards.
5.1 Types of Audits
There are several types of audits:
- Internal Audits: Conducted by an organization's own staff to assess internal controls.
- External Audits: Performed by independent auditors who evaluate the accuracy of financial statements.
- Forensic Audits: Investigate suspected fraud or financial discrepancies.
Each type serves distinct purposes within an organization’s governance structure.
5.2 The Audit Process
The audit process typically involves several steps:
- Planning: Setting objectives and determining the scope of the audit.
- Fieldwork: Gathering evidence through testing transactions and reviewing documentation.
- Reporting: Presenting findings in an audit report that outlines any discrepancies or areas for improvement.
5.3 Significance of Auditing for Organizations
Auditing enhances transparency by assuring that financial statements are accurate and compliant with regulations, fostering trust among stakeholders.
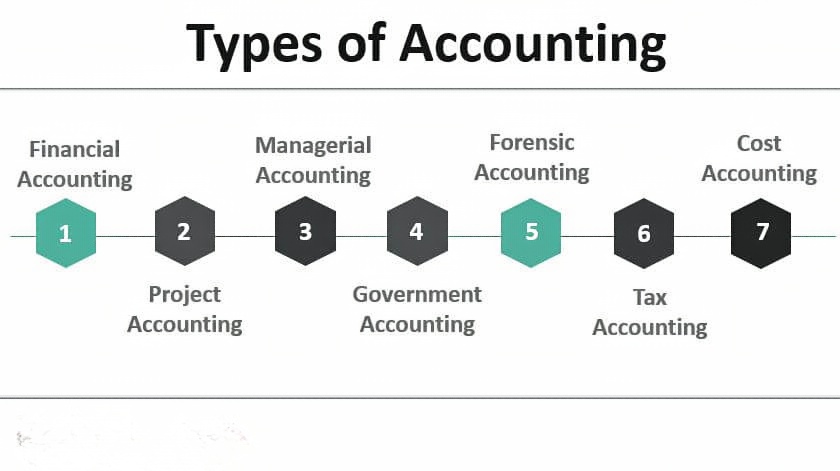
6. Forensic Accounting
Forensic accounting investigates financial discrepancies for legal purposes, often involving fraud detection.
6.1 Definition and Scope
Forensic accounting combines accounting skills with investigative techniques to uncover fraud or misconduct within an organization’s finances.
6.2 Techniques Used in Forensic Accounting
Common techniques include:
- Data Analysis: Using software tools to analyze large volumes of data for anomalies.
- Interviews: Conducting interviews with employees or stakeholders involved in suspicious activities.
- Document Examination: Reviewing contracts, invoices, or other documentation for inconsistencies.
These techniques help forensic accountants gather evidence needed for legal proceedings.
6.3 High-profile Cases
Notable cases such as the Enron scandal highlight the importance of forensic accounting in detecting fraud before it escalates into larger issues affecting shareholders and employees alike.
7. Government Accounting
Government accounting manages public funds while ensuring accountability in public spending.
7.1 Overview of Governmental Accounting Standards
Governmental accounting follows specific standards such as Generally Accepted Accounting Principles (GAAP) tailored for public sector entities to ensure transparency and accountability in managing taxpayer dollars.
7.2 Role of Government Accountants
Government accountants are responsible for tracking public funds, preparing budgets, conducting audits, and ensuring compliance with regulations governing public finance management.
7.3 Importance of Public Trust
Effective government accounting fosters trust among citizens by ensuring that public funds are used efficiently and transparently, ultimately contributing to better governance.
8. International Accounting
International accounting addresses global standards and practices necessary for multinational corporations operating across borders.
8.1 Global Accounting Standards
Key frameworks like International Financial Reporting Standards (IFRS) guide international accounting practices by providing consistency in financial reporting across countries.
8.2 Challenges in International Accounting
Accountants face challenges such as differing regulatory environments, currency exchange rate fluctuations, and cultural differences affecting business practices when operating globally.
8.3 Case Studies of Multinational Corporations
For instance, a multinational corporation may need to consolidate its financial statements from subsidiaries operating under different regulatory frameworks into one coherent report compliant with IFRS standards—highlighting the complexities involved in international accounting practices.
9. Environmental Accounting
Environmental accounting evaluates the economic impacts of environmental decisions made by organizations.
9.1 Definition and Relevance
Environmental accounting focuses on incorporating environmental costs into financial reporting to assess sustainability initiatives' economic impacts effectively.
9.2 Tools for Environmental Accounting
Methods such as life cycle costing (LCC) allow organizations to evaluate the total cost associated with a product's lifecycle—from production through disposal—enabling better decision-making regarding sustainability efforts.
9.3 Case Studies on Sustainability Reporting
Companies like Unilever have successfully utilized environmental accounting principles to enhance their sustainability reporting practices, demonstrating accountability toward environmental impacts while appealing to socially conscious consumers.
10. Nonprofit Accounting
Nonprofit accounting tracks funds while ensuring compliance with regulations specific to nonprofit organizations.
10.1 Unique Aspects of Nonprofit Accounting
Nonprofit organizations operate differently than for-profit entities; they focus on fund tracking rather than profit maximization—requiring specialized knowledge regarding donor restrictions and grant compliance requirements.
10.2 Importance of Transparency
Transparency is critical in nonprofit accounting; clear reporting helps maintain donor trust by demonstrating responsible stewardship over contributed funds while ensuring compliance with regulatory requirements governing nonprofits’ operations.
10.3 Examples of Best Practices
Best practices include implementing robust internal controls over fund management processes—ensuring timely reporting on expenditures against budgets—to enhance operational effectiveness within nonprofits while building credibility with stakeholders.
Conclusion
Understanding the various types of accounting is essential not only for professionals in the field but also for stakeholders who rely on accurate financial information for decision-making purposes across different sectors—each type serving distinct yet interconnected roles within an organization’s overall framework! By grasping these nuances better equipped individuals can navigate today’s complex business landscape more effectively!